This article includes insights, analysis, and other contributions from Senior Analyst, Fred McClimans
The News: Marvell Technology, Inc. (NASDAQ: MRVL) reported first quarter results for fiscal 2022 after market close on June 7, 2021, beating analyst expectations for both revenue and earnings.
Here’s a quick breakdown of key numbers versus expectations:
- Revenue: $832 million versus $807 million expected
- Earnings: $0.29 per share (non-GAAP diluted) versus $$0.27 per share expected
Per the company:
“We began fiscal 2022 on a strong note, with stand-alone Marvell revenue growing 17% year-over-year for the first quarter. The acquisition of Inphi increases and accelerates our growth opportunity in the data center, Marvell’s largest end market by revenue,” said Matt Murphy, Marvell’s President and CEO. “Marvell’s outlook for strong revenue growth in the second quarter highlights robust demand across all our key end markets.”
You can read the full release on Marvell’s Investor Page
Marvell’s Q1 Earnings Results Are, Well, Pretty Marvelous, In Spite of Everything
Analyst Take: Marvell’s Q1 earnings were, in fact, pretty marvelous, especially in light of the significant supply chain issues that the semiconductor is currently navigating. With these results, Marvell now has five consecutive quarters of accelerated earnings growth, a trend we expect to continue given its strong market position and its aggressive guidance for the upcoming second quarter of fiscal 2022:
- Net revenue is expected to be $1.065 billion +/- 3%
- GAAP gross margin is expected to be 34.8% to 37.5%
- Non-GAAP gross margin is expected to be approximately 64%
- GAAP operating expenses are expected to be $633 million to $643 million
- Non-GAAP operating expenses are expected to be $370 million to $375 million
- Basic weighted average shares outstanding are expected to be 822 million
- Diluted weighted average shares outstanding are expected to be 835 million
- GAAP diluted loss per share is expected to be $(0.37) +/- $0.04 per share
- Non-GAAP diluted income per share is expected to be $0.31 +/- $0.03 per share
Based on this guidance and Marvell’s Q1 earnings performance the stock rose 5% after earnings. The company is also benefitting from a number of upgrades and upward-revised price targets from 9 Wall Street analyst firms.
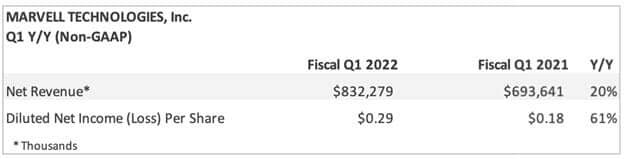
Year over year, Marvell’s performance was solid:
The Impact of Marvell’s Inphi Acquisition
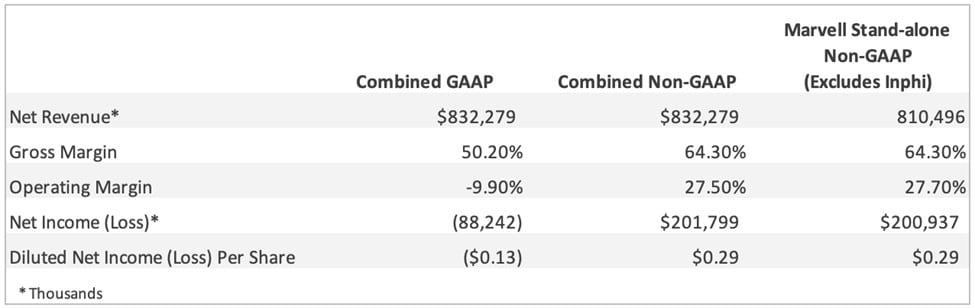
This was the first quarter to feature the boost of Marvell’s $10 billion acquisition of Inphi, completed after receiving clearance from China’s regulatory body. The deal closed only 10 days prior to the end of its quarter and had minimal impact on the quarterly results:
Inphi is a chip maker focused on connecting data center servers and data centers over fiber optic cables. Long-term this will be a significant benefit to Marvell, augmenting its copper-based data center products.
As Marvell’s President and CEO, Matt Murphy sees it:
“The acquisition of Inphi increases and accelerates our growth opportunity in the data center, Marvell’s largest end market by revenue. Marvell’s outlook for strong revenue growth in the second quarter highlights robust demand across all our key end markets. I have never felt stronger about our prospects and believe that we are at the beginning of a multiyear growth cycle.”
We share this sentiment. Combined, we believe the new Marvell is on its way to establishing a strong competitive moat as a provider of semiconductors to the rapidly growing data center market.
Marvell’s ability to quickly make the Inphi acquisition fully accretive in its next full quarter results should be considered a positive for the company as often acquisitions of this size can take a few quarters before this happens. Investors will be able to clearly see the impact of the acquisition on the earnings results as the more significant synergies begin to take place within the company.
Another notable announcement that came from this quarter’s earnings result was a new, more transparent delivery of earnings results that will help investors better understand Marvell’s execution against its strategy. Currently, the company breaks its revenues into only two buckets for storage and networking. Moving forward, the company will segment to include carrier, data center & cloud, and automotive. The company will update results 7 quarters in arrears as well, to show the trend lines across these businesses. I like this move, as it adds transparency and accountability to the company’s execution.
Addressing the Chip Shortage
As we mentioned above, the semiconductor industry is in the midst of a production crisis that has resulted in shortages of many commonly used chips and forced many industries from automotive to consumer electronics to slow or halt manufacturing operations. This is both a short-term challenge due to pandemic and trade-based supply chain issues, as well as a long-term challenge in terms of limited fabrication facilities.
Marvell, a fab-less provider that sources the actual fabrication of its chips to third-party fabs, addressed this during its earnings call and appears to be in a good position with enough guaranteed manufacturing and materials to continue to grow per its plans, although the firm did acknowledge that demand for the company’s products exceeds its ability to deliver at this time.
If the company is able to creatively address this issue and boost production, we would expect its growth of the coming quarters to improve as well.
The Forward Look for Marvell
It’s been a busy quarter for Marvell. In addition to closing on the Inphi acquisition, the company recently announced its new Bravera SC5 SSD controller, a move that we believe will be in high demand as data center operators continue to advance the deployment of flash (solid state) drives in support of applications and workloads that demand faster data access and lower latency.
The company also unveiled its Atlas™ 50Gbps PAM4 DSP, an integrated chipset solution that lowers cost/bit processing (key for hyperscale data center operators) with performance metrics designed to meet the high-performance requirements of AI-based applications such as machine learning and predictive analytics.
And this past April, the company announced its 802.3ch 10G Ethernet PHY as part of its move to aggressively target the automotive industry’s growing requirement for high-performance, in-vehicle communications for connected car systems.
We are also positive on the company’s new reporting mechanisms, which should help investors better understand Marvell’s business and hold the company more accountable to execution across segments.
We’ll continue to follow Marvell closely to see how well it integrates the Inphi acquisition and how it deals with potential fab or supply chain issues impacting the overall industry. But from our perspective, Marvell is in very good shape to continue its impressive growth through the remainder of the calendar year and into the next.
Futurum Research provides industry research and analysis. These columns are for educational purposes only and should not be considered in any way investment advice.
More insights from Futurum Research:
Marvell Takes Data Center Flash Storage to The Next Level With Bravera SC5 SSD Controller Debut
Marvell Rapidly Strengthens IVN Proposition with New 10G Ethernet PHY Offering
Marvell Octeon DPU Family Boards the Burgeoning Evenstar Initiative
Image Credit: Investor’s Business Daily
Author Information
Daniel is the CEO of The Futurum Group. Living his life at the intersection of people and technology, Daniel works with the world’s largest technology brands exploring Digital Transformation and how it is influencing the enterprise.
From the leading edge of AI to global technology policy, Daniel makes the connections between business, people and tech that are required for companies to benefit most from their technology investments. Daniel is a top 5 globally ranked industry analyst and his ideas are regularly cited or shared in television appearances by CNBC, Bloomberg, Wall Street Journal and hundreds of other sites around the world.
A 7x Best-Selling Author including his most recent book “Human/Machine.” Daniel is also a Forbes and MarketWatch (Dow Jones) contributor.
An MBA and Former Graduate Adjunct Faculty, Daniel is an Austin Texas transplant after 40 years in Chicago. His speaking takes him around the world each year as he shares his vision of the role technology will play in our future.