Qualcomm Earnings Need a Deeper Look — Here’s Why

As the header image here shows, the Street’s assessment that “while Qualcomm Q2 earnings exceed analyst forecasts, the stock price fell on weak guidance” is flat out crazy. Here’s why. The Street knows that Apple is very unlikely to release a Qualcomm-powered iPhone (and possibly an AR product) until HR 2020.

This could be interpreted as Qualcomm chipset sales and licensing revenue will not benefit from an “Apple boost” until next year, which is fair. The good news is that the Apple Qualcomm war is over. The bad news is that the resulting net new revenue boost for Qualcomm won’t be immediate.

Also, Qualcomm and Apple still need a the FTC’s lawsuit to either fizzle out or come to a positive settlement. As long as that sword is still hanging over Qualcomm’s head, investors may feel a little nervous. Investors prefer certainty over the other thing. Fair enough.

Phone sales, by all manufacturers, aren’t exactly stellar this year, so chipmakers probably need to talk more to the Street about how IoT growth could fill that gap.

And finally, 5g is still in very early stages of deployment, so revenue from 5G won’t really scale in 2019-2020. Not yet.

Analysts on the Street tend to focus more on short-term guidance, which means a focus on quarterly and year-over-year metrics. As a tech analyst, I tend to gauge company performance in the tech industry based on a longer runway—one predicated on 18+ month innovation and product development life cycles. This means I am always looking to the next 18 to 36 months, not the next 3 to 12. From that perspective, I expect that both Apple and Qualcomm will see a significant improvement in revenues in 2020 as their combined innovation pulls Apple out of its hardware slump. And yes, you didn’t imagine it. I did bring up Apple, Augmented Reality (AR), and Qualcomm in the same conversation. Listen, it’s just a hunch, but I don’t think Apple had any chance whatsoever of releasing a viable wireless AR product anytime soon without Qualcomm’s involvement.

Here are specifics on share price from MarketWatch: Qualcomm QCOM, +4.39% shares declined 1% in premarket trading Thursday , following a 0.2% rise to close Wednesday’s regular session at $86.37. Shares are up 52% on the year. In comparison, the PHLX Semiconductor Index SOX, +1.97% is up 34%, while the S&P 500 index SPX, +0.19% is up 17%, and the tech-heavy Nasdaq Composite Index COMP, +0.42% is up 21%.

Futurum Research provides industry research and analysis. These columns are for educational purposes only and should not be considered in any way investment advice. 

More relevant reads from the Futurum team on this topic:

Apple Earnings: The Bright Spots and the Not-So-Bright Spots

Apple, Qualcomm Settle Royalty and Patent Dispute

Author Information

Olivier Blanchard

Olivier Blanchard is Research Director, Intelligent Devices. He covers edge semiconductors and intelligent AI-capable devices for Futurum. In addition to having co-authored several books about digital transformation and AI with Futurum Group CEO Daniel Newman, Blanchard brings considerable experience demystifying new and emerging technologies, advising clients on how best to future-proof their organizations, and helping maximize the positive impacts of technology disruption while mitigating their potentially negative effects. Follow his extended analysis on X and LinkedIn.
Related Insights
Stellantis Q3 FY 2026 Earnings Show Cost Cuts Offsetting a Weak Europe
November 2, 2026

Stellantis Q3 FY 2026 Earnings Show Cost Cuts Offsetting a Weak Europe

Olivier Blanchard, Research Director and Practice Lead, Intelligent Devices at The Futurum Group, reviews Stellantis' Q3 FY 2026 earnings, Value Creation Program cost gains, North America's recovery, and Europe's margin...
Texas Instruments Q3 FY 2026 Earnings Beat as Data Center Sales Nearly Double
November 2, 2026

Texas Instruments Q3 FY 2026 Earnings Beat as Data Center Sales Nearly Double

Brendan Burke, Research Director, Semiconductors, Supply Chain & Emerging Tech at Futurum, reviews Texas Instruments' Q3 FY 2026 earnings, data center growth, a new industrial peak, and capacity-driven pricing gains....
Intel Q3 FY 2026: Xeon Demand Tests Supply as PC Spending Weakens
November 2, 2026

Intel Q3 FY 2026: Xeon Demand Tests Supply as PC Spending Weakens

Futurum Research analyzes Intel’s Q3 FY 2026 earnings, examining Xeon demand, PC purchasing constraints, and foundry execution as manufacturing capacity shapes its AI opportunity....
Intel's Substrate Shortage Moves the CPU Supply Chain Bottleneck Into the Package
October 30, 2026

Intel's Substrate Shortage Moves the CPU Supply Chain Bottleneck Into the Package

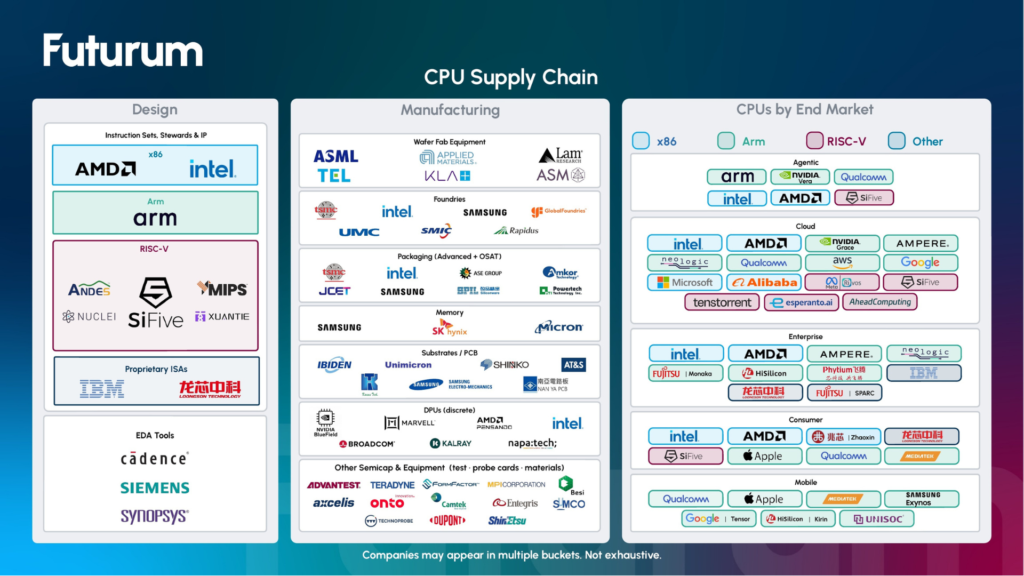
Brendan Burke, Research Director at Futurum, presents Futurum's CPU Supply Chain market map and examines which suppliers gain from Intel's substrate shortage as a server CPU market poised to grow...
Quantum Computing Will Break AI’s Science Barrier and Open a $1.5 Trillion Addressable Market by 2040
October 29, 2026

Quantum Computing Will Break AI’s Science Barrier and Open a $1.5 Trillion Addressable Market by 2040

AI took 15 years to disrupt knowledge work, and quantum has just produced its 2012 moment. Futurum sizes the breakthroughs quantum will deliver and the $1.51 trillion addressable market they...
NXP Q3 FY 2026 Data Center and Physical AI Broaden Growth
October 29, 2026

NXP Q3 FY 2026: Data Center and Physical AI Broaden Growth

Futurum Research analyzes NXP’s Q3 FY 2026 earnings, focusing on vehicle content gains, industrial edge AI adoption, and data center control systems....

Book a Demo

Welcome

The vision behind everything in Futurum’s Custom Research practice is this: research should show you what is happening, what comes next, and what to do about it. It should be personal to each audience, easy for people to grasp, and structured so LLMs can reason over it accurately. And it should be fast and turnkey; you want answers now, not another project to carry for quarters.

Whether you are defining business, channel, or go-to-market strategy; evaluating vendors or justifying ROI; or commissioning research to fill an emerging market need, we have your back, with a program that answers your questions with the objectivity and credibility to drive real decisions.

To do it, we bring unmatched data to bear: Futurum research, surveys, and market projections; validated market feeds; ETR’s 15 years of insight from 10,000 technology decision-makers; G2’s buyer and user data; and what our analysts hear every day. Add leading primary collection, from AI-moderated voice interviews to surveys and analyst-led interviews, all turnkey, and every project comes out credible, nuanced, and actionable.

And we don’t just drop the results in your lap. For internal work, we provide analyst-led sessions, interactive dashboards, and a range of formats. For market-facing work, Futurum delivers turnkey activation and amplification that actually gets seen, by people and by LLMs, through our media and share of voice. This is research that moves decisions and markets.

We will meet you wherever you are, from a fast-turn brief to a multi-year program, and shape the work to your goals, timeline, and budget. The right program for your moment.

If any of this is useful, I would love to talk.

Benjamin Brown, VP Custom Research, Futurum Research

Benjamin Brown

VP, Custom Research · The Futurum Group

Newsletter Sign-up Form

Get important insights straight to your inbox, receive first looks at eBooks, exclusive event invitations, custom content, and more. We promise not to spam you or sell your name to anyone. You can always unsubscribe at any time.

All fields are required


Thank you, we received your request, a member of our team will be in contact with you.